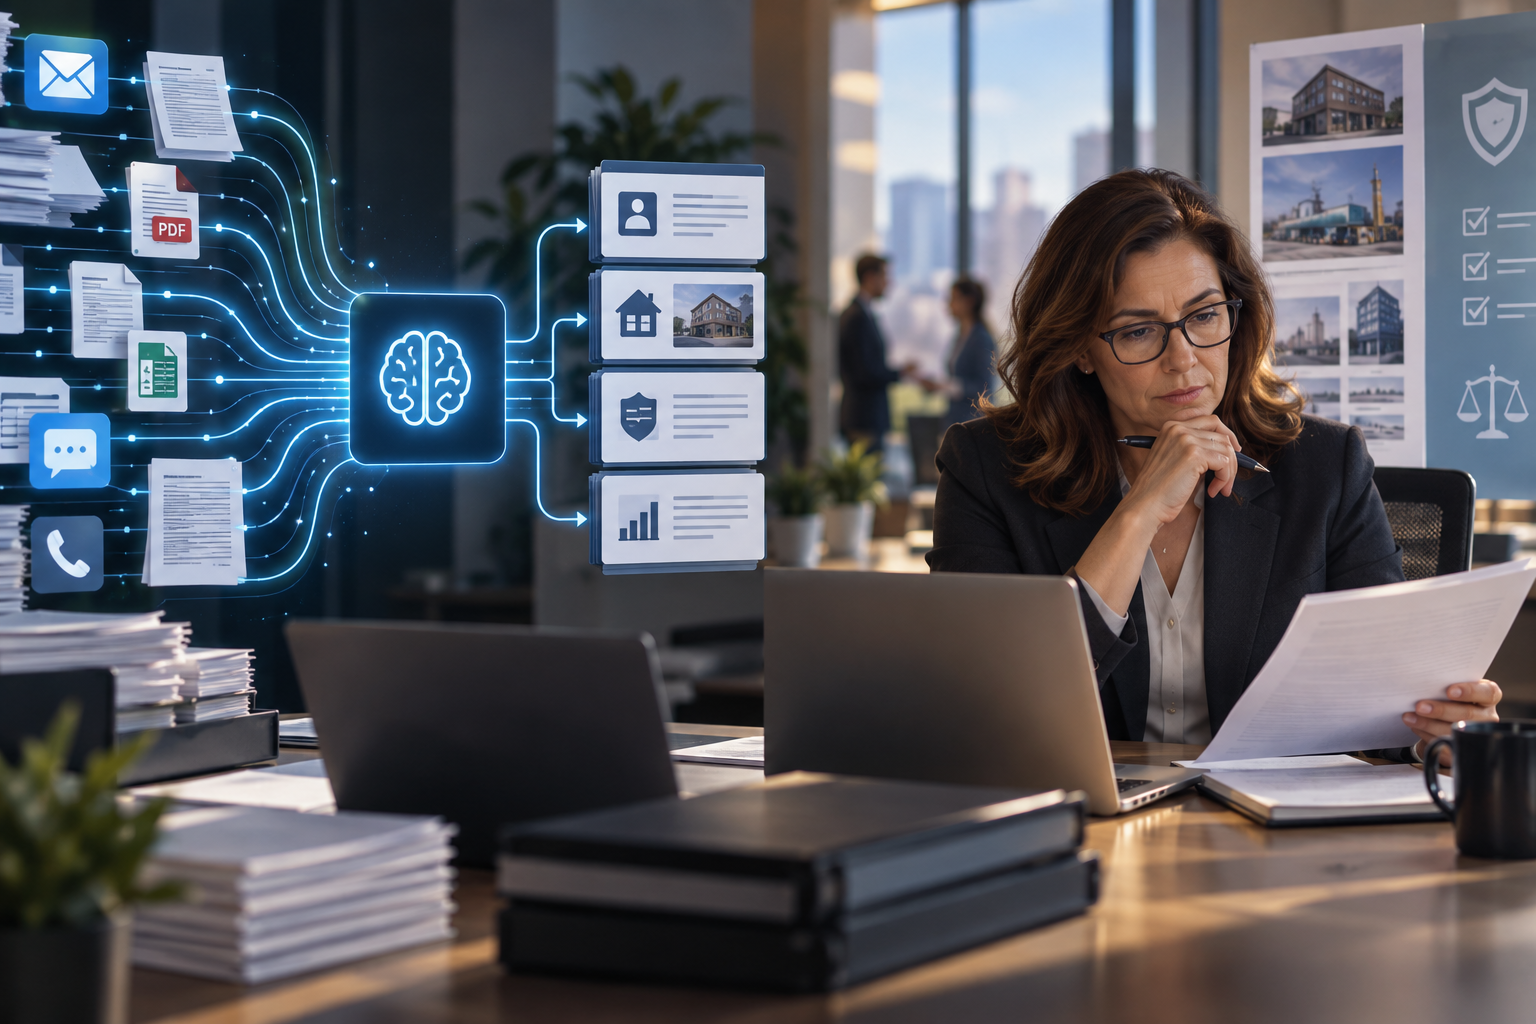
When an insurance broker asks for coverage, the request may arrive as an email, a phone message, a text, or a form from another company. The information may be spread across several documents. Before an experienced underwriter can decide whether the risk is a good fit, someone may have to read the material, copy details into another system, and chase missing information.
That busywork is the part of insurance that artificial intelligence may be able to handle well. The judgment about the risk is different. It still belongs with people who understand the customer, the market, and the details that do not fit neatly into a form.
The first step is sorting the information
A submission is simply the information sent to an insurance company when someone wants coverage. It might describe a building, a business, a vehicle, or another kind of risk. The information can arrive in different forms and may not be organized in the same way each time.
In a report for Insurance Business, journalist Chris Davis spoke with Tatum Fish, a strategic value architect at Cytora, about where AI can help in insurance. Fish's point was practical: the goal is not to replace the underwriter. The goal is to remove the work that keeps the underwriter from doing the part that needs experience.
That could include gathering submissions from email, phone calls, text messages, and carrier websites. It could also include reading documents, pulling out basic details, putting those details in the right place, and showing the underwriter what still needs attention. Applied Systems' email-to-quote tool was offered as one example of this kind of approach.
The benefit is not that a machine suddenly knows which customer to accept. The benefit is that the person making the decision can spend less time typing the same information into several places.
Judgment is more than finding a pattern
Insurance decisions often involve questions that do not have one obvious answer. A business may have unusual circumstances. A building may have a history that needs explanation. A customer may be a strong fit for reasons that do not appear in a simple checklist. An experienced underwriter may notice a concern, ask a better question, or recognize an opportunity that a basic sorting tool would miss.
That is why the division of work matters. AI can help process a large amount of information quickly. It can organize the details and point out what is missing. A human underwriter can then examine the risk, weigh the unusual parts, speak with brokers, and decide what makes sense. The person remains responsible for the choice.
This also protects the knowledge that experienced employees have built over many years. If a system quietly makes every decision, newer staff may never learn how those decisions are made. A tool that prepares information for review can support the team without hiding the reasoning behind the final answer.
Start with the problem, not the promise
Fish's advice also applies outside insurance: do not begin with the question, “Where can we use AI?” Begin with, “Where are people losing time on work that does not require their best judgment?”
That question can reveal a smaller and safer place to begin. Maybe a team spends hours moving information from one document to another. Maybe staff members search through several inboxes to find new requests. Maybe an underwriter has to ask for the same missing detail on every submission. These are clear problems that can be measured before and after a change.
A company can then ask simple questions. Did the team spend less time on copying and sorting? Are fewer details being missed? Can underwriters review more requests without rushing? Are customers and brokers receiving clearer answers? If the answer is no, the process needs more work. The presence of an AI tool is not proof that the business improved.
The people doing the work should help design it
The employees who handle submissions every day often know the weak points better than anyone else. They know which documents arrive in strange formats, which details are usually missing, and where a new step could create another delay. They also know which parts of the work require care and which parts are simply repetitive.
Those employees should be included before a new tool is chosen and while it is being tested. They can help the business decide what the tool should prepare, what a person must check, and what should stop until someone reviews it. This is especially important in insurance, where a shortcut that looks efficient on paper can create confusion or a poor decision later.
The Insurance Business report describes this as a need for cooperation among insurers, technology companies, underwriters, brokers, and frontline staff. A tool that works in a demonstration may still need to be adjusted to fit the way a real team handles its work. Insurance companies are not necessarily refusing to change. Many are working with processes built over decades, and those processes cannot be replaced responsibly with a single button.
A better division of labor
The strongest use of AI in insurance may be the least dramatic one. Let it collect, read, sort, and prepare information. Let people ask questions, understand the situation, weigh the risk, and make the decision.
That approach does not promise that every task will become faster or that every error will disappear. It does give a team a clear place to begin and a clear limit to protect. The question is not whether AI should be everywhere. The question is which part of the work can be made easier without taking away the judgment that customers and businesses still need.
For insurance teams, that may be the difference between using AI as a useful assistant and turning it into an unclear decision-maker. The best result is not a machine replacing the underwriter. It is an underwriter with more time for the work only an experienced person can do.